About the Course
Introduction
This CLE/CPE course will provide estate planning counsel and advisers with a comprehensive and practical guide to structuring defined value formula clauses to avoid gift tax consequences on asset transfers. The speaker will provide specific guidance on making formula allocations to withstand IRS scrutiny and identify conditions in transfer structures that trigger gift tax imposition.
Description
The use of defined value clauses to mitigate gift tax impact on the transfer of hard to value assets has long been an item of IRS scrutiny. While the IRS lost several tax court challenges to defined value clauses, it continues to take an adverse audit position and seek suitable new cases to take to court.
Several defined value clauses have withstood IRS scrutiny, utilizing both formula allocations and price adjustment clauses. Proper implementation of the transfer is critical to structuring a defined value clause, and there must be no prearrangement between the transferor and the transferee.
In the current environment with an increased exemption amount, estate planning advisers should protect lifetime transfers from unintended gift tax with a well-designed defined value clause. Because the IRS will continue to scrutinize the construction and implementation of defined value clauses, estate planners must carefully draft and strictly implement the provisions according to their terms.
Listen as our speaker provides comprehensive guidance on structuring defined value clauses that will withstand IRS scrutiny and challenges and addresses recent developments impacting the use of these formula clauses in trusts and estate planning. The speaker will review specific language designed to be as robust as possible if challenged yet flexible enough to be used in multiple contexts.
Presented By
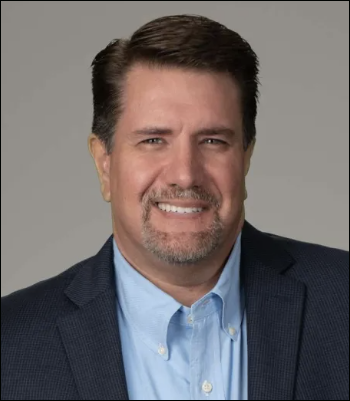
Mr. Meek is a partner in MendenFreiman's business law, tax planning, and estate planning practice areas. He provides comprehensive legal counsel on business, tax, and estate planning matters to high-net-worth individuals and families, as well as privately-held businesses. A solutions-oriented, pragmatic, and collaborative counselor with strong business and financial acumen, experience advising families and business leaders on wealth and business planning issues, and aptitude in balancing risk exposure against strategic goals, Mr. Meek has represented businesses and business owners with the design and implementation of comprehensive business plans that integrate succession, tax minimization, and asset protection techniques. He applies his knowledge and expertise to develop customized strategies that help clients achieve their long-term business, financial, and estate planning objectives. Throughout his career, Mr. Meek has worked on numerous high-net-worth, developing comprehensive estate, tax, wealth transfer, and business succession plans and managing formation and implementation processes for defective grantor trusts and other forms of dynastic trusts, estate freeze transactions, and charitable trusts and foundations.
-
This 90-minute webinar is eligible in most states for 1.5 CLE credits.
-
Date + Time
- event
Tuesday, April 28, 2026
- schedule
1:00 p.m. ET./10:00 a.m. PT
I. Types of defined formula value approaches
A. Formula allocation clause based on a subsequent agreement of involved parties
B. Formula allocation clause based on final values as determined for gift tax purposes
C. Price adjustment clauses
II. Impact of recent cases
III. Exercising substitution powers using a defined value clause
IV. Traps to avoid
The speaker will review these and other noteworthy issues:
- What are the grounds for IRS challenges of defined value clauses?
- What types of defined value clauses have failed to withstand IRS challenges?
- How to best structure defined value clauses
- How to structure defined value clauses involving non-taxable transfers other than to public charities
Related Courses
Estate Planning for U.S. Families with Foreign Assets: Strategies for Tax Counsel and Estate Planners
Tuesday, January 26, 2027
1:00 PM ET/10:00 AM PT
Income Tax Planning for In-Kind Trust Distributions
Tuesday, February 16, 2027
1:00 PM ET/ 10:00 AM PT