About the Course
Introduction
This webinar will discuss the U.S. limitations on interest deductions for multinational companies, thin capitalization restrictions in other countries, OECD recommendations for interest limitation rules, and the impact of recent U.S. legislative changes and global minimum tax initiatives on cross-border financing structures. Our panel of seasoned international tax professionals will review Sections 163(j) and 267(a)(3) for U.S. restrictions, analyze similar limitations overseas, and provide suggestions for structuring related-party debt to lower the overall tax burden of international taxpayers.
Description
Multinational corporations have historically structured loans with related companies in low-tax countries, creating large interest deductions that lower domestic taxes paid in high-tax jurisdictions—more or less converting equity into debt. Many countries, including the U.S., restrict these transactions through interest limitation legislation.
Recent developments have significantly altered the international financing landscape. The restoration of a more favorable EBITDA-based computation under Section 163(j), evolving earnings-stripping regimes in Europe and other jurisdictions, and the implementation of OECD Pillar Two global minimum tax rules have created new challenges and planning opportunities for multinational groups. In addition, Section 267(a)(3) continues to play a critical role in determining the timing of deductions for interest paid to foreign related parties. Tax advisers must understand how these rules interact when evaluating financing structures, modeling interest limitations, and managing worldwide effective tax rates.
Listen as our accomplished panel of international tax practitioners examines the latest developments affecting cross-border interest deductions, multinational financing arrangements, OECD initiatives, and practical strategies for maximizing available deductions.
Presented By
Ms. Belyavskaya has 15 years of experience working with multinational businesses and high-net-worth individuals. She provides tax compliance and advisory services on cross-border transactions, corporate international restructuring, U.S. entity formation and dissolution issues, as well as global mobility matters and expatriate tax assistance. Ms. Belyavskaya has worked with numerous clients and PKF colleagues around the world on transfer pricing issues and U.S. nexus tax regulations. She has prepared numerous memoranda regarding U.S. tax implications for foreign clients, and she is a contributor to the Firm’s Thought Leadership series. Currently, Ms. Belyavskaya is spearheading the Firm’s efforts to grow its client base in the Commonwealth of Independent States (CIS) in Eastern European and Asian countries.
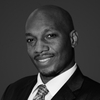
Mr. Ford has more than 20 years of experience advising private equity sponsors, middle-market companies, multinational organizations and business owners on complex transactions. He specializes in buy-side and sell-side tax due diligence, transaction structuring, tax modeling and identifying and mitigating federal, state and international tax risks. Throughout his career, Mr. Ford has advised on transactions ranging from less than $1 million to more than $2 billion. He has developed particular expertise in Section 1202 planning, F reorganizations, tax attribute optimization, renewable energy tax credits and post-closing integration. Mr. Ford is also a recognized technical educator and thought leader. He has authored articles on complex tax matters, led national training programs and taught a master’s-level course on mergers and acquisitions at Yeshiva University.
.jpg)
Mr. Parmegiani has over 30 years of experience in public accounting. He has considerable expertise in a broad range of tax specialty areas, including the hospitality and real estate industries, both domestic and international business investments, sales and use tax, C Corporations, S Corporations, Partnerships, LLCs and REITs, and state and local tax issues. Mr. Parmegiani has worked extensively with high net worth individuals, including United States taxpayers living abroad and foreign nationals living in the United States and advises foreign groups in establishing domestic business operations. He has years of experience in cross border tax structuring, transfer pricing issues and tax examination representation. Mr. Parmegiani heads up the Firm’s international tax practice, is a member of the Firm’s Tax Leadership Committee and is Chairman of PKF International’s Internationally Mobile Individual Tax Committee.
-
BARBRI is a NASBA CPE sponsor and this 110-minute webinar is accredited for 2.0 CPE credits.
-
BARBRI is an IRS-approved continuing education provider offering certified courses for Enrolled Agents (EA) and Tax Return Preparers (RTRP).
Date + Time
- event
Tuesday, December 15, 2026
- schedule
1:00 PM ET/10:00 AM PT
I. Introduction: deducting interest overseas
II. U.S. rules
A. Section 163(j) after OBBBA
B. Section 267(a)(3)
C. IRS Fact Sheet 2026-14
III. Thin capitalization and earnings stripping rules
IV. OECD developments
V. Structuring considerations for related-party debt
The panel will review these and other key issues:
- OBBBA's changes to Section 163(j)'s adjusted taxable income computation
- Section 267(a)(3)'s cash-method requirement for related foreign party interest
- OECD Pillar Two developments affecting multinational debt structuring
- Practical strategies for structuring international debt arrangements
Learning Objectives
After completing this course, you will be able to:
- Identify specific countries' responses to international debt shifting by MNCs
- Determine how 267(a)(3) affects interest deductions between MNC related parties
- Decide how OECD's recommendations impact rules limiting interest deductions
- Ascertain how 163(j) restricts foreign taxpayers' interest deductions
- Field of Study:
- Level of Knowledge: Intermediate
- Advance Preparation: None
- Teaching Method: Seminar/Lecture
- Delivery Method: Group-Internet (via computer)
- Attendance Monitoring Method: Attendance is monitored electronically via a participant's PIN and through a series of attendance verification prompts displayed throughout the program
- Prerequisite:
Three years+ business or public firm experience preparing complex tax forms and schedules, supervising other preparers or accountants. Specific knowledge and understanding of international taxation, including residency determination, foreign entity classifications, application of treaty benefits, as well as GILTI/NCTI, Subpart F, and the related Section 250 deductions.
BARBRI, Inc. is registered with the National Association of State Boards of Accountancy (NASBA) as a sponsor of continuing professional education on the National Registry of CPE Sponsors. State boards of Accountancy have final authority on the acceptance of individual courses for CPE Credits. Complaints regarding registered sponsons may be submitted to NASBA through its website: www.nasbaregistry.org.
BARBRI is an IRS-approved continuing education provider offering certified courses for Enrolled Agents (EA) and Tax Return Preparers (RTRP).
BARBRI CE webinars-powered by Barbri-are backed by our 100% unconditional money-back guarantee: If you are not satisfied with any of our products, simply let us know and get a full refund. Contact us at 1-800-926-7926 .
Recommended Resources